
SC Lays Down Principles For Testing Movability vs. Immovability
To resolve the issue, the Court first examined whether mobile towers and PFBs could be classified as movable property in the form of “goods”. While deciding this issue, the Court laid down
Telecommunication towers are movable property and not immovable,
The Respondents contended that telecommunication towers constitute immovable property as they are fixed to earth or buildings, and the specific exclusion of telecom towers from the
Supreme Court rules mobile towers movable, ITC permitted under
The Court ruled that telecom towers do not satisfy criteria for “immovable property” because they can be dismantled, relocated, and are not permanently attached to the ground. While
19.08.2025: Telecommunication towers, being movable and essential
The Delhi High Court held that telecommunication towers, being capable of dismantling and relocation without loss of functionality, do not qualify as immovable property within the meaning of Section 17
ITC on Telecommunication Towers available under the GST regime
Applying these principles, the Court concluded that telecommunication towers are movable property. The towers are installed using bolts and nuts and can be dismantled, moved, and reassembled at
Paradox of Permanence: Telecom Towers ''Bolted To Ground'' Still
Courts ruled that telecom towers remain movable goods because they can be dismantled and relocated, even when bolted to concrete foundations. The decision preserves GST
Delhi High Court Defines Telecom Towers as Movable Property under
Rebutting the aforementioned submissions, the Respondent submitted that the exclusion of telecom towers from the definition of ''plant and machinery'' implied that they ought to be classified as
Telecommunication towers are movable property and not immovable,
The Supreme Court held that telecommunication towers are movable goods because they are manufactured off-site, assembled on-site, can be dismantled without structural damage, and
Supreme Court Ruling: Supreme Court Supports Telecom Towers''
The Supreme Court on Friday upheld a Delhi High Court''s December ruling that favoured Bharti Airtel and Indus Tower, holding that telecom towers qualify as "movable" property and thus
Mobile Towers Are Not Immovable Property, They Are
The Delhi High Court has held that mobile/ telecommunication towers are movable properties, eligible for availing input tax credit under the
Telecommunication Towers Are Not Immovable Property – ITC Is
Commissioner noted that though the decisions were rendered in the context of the Cenvat Credit Rules, 2004, the decisions, on application of the generic principles which would apply to the
Telecom towers are moveable property, eligible for ITC: Delhi HC
Delhi High Court rules telecom towers as movable property, eligible for Input Tax Credit (ITC) under GST, addressing exclusions in Section 17 (5) of the CGST Act.
Delhi High Court Clarifies Telecom Towers as Movable Properties
Therefore, the petitioners are entitled to avail input tax credit on telecom towers as movable properties under the CGST Act. The judgment has been hailed as a significant step in
Supreme Court classifies telecom towers as movable property for GST
Supreme Court upholds Delhi High Court ruling on telecom towers as movable property for GST input tax credit.
Towers and Shelters are not Immovable Properties: Cenvat Credit
The towers which are received in CKD condition, are assembled/ erected at the site subsequently giving rise to a structure that remains immovable till its use because of safety, stability
Delhi High Court Defines Telecom Towers as Movable Property under
Telecom towers do not fall within the ambit of s. 17 (5) (d) of the CGST Act, which restricts ITC on goods and services used for constructing immovable property. It was further submitted that telecom towers
ITC on Telecommunication Towers available under the GST regime
Dhruva Comments: The Court''s emphasis on the five precepts for qualification of immovable property has clarified the classification of telecommunication towers as movable property, setting a strong
Telecommunication towers are movable property and not immovable,
The High Court correctly concluded that this exclusion does not automatically classify towers as immovable property - they must independently satisfy immovability tests. Similarly in the
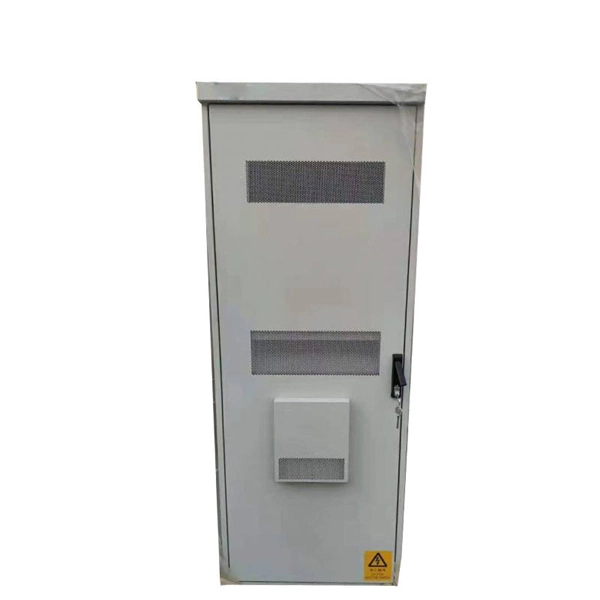
This reference is intended for preliminary fiber and communications infrastructure research. Optical interface, fiber type, port or core capacity, electrical input and output, enclosure protection, cooling, installation limits and applicable standards must be verified for the specific project.